The Edge Is Structural, Not Predictive
Most traders chase the wrong thing. They try to predict where SPX goes next. The professionals do something completely different — they harvest a structural mispricing that shows up in option prices day after day, whether the market goes up, down, or nowhere.
That mispricing is the Volatility Risk Premium (VRP): implied volatility — the volatility baked into option prices — is persistently higher than the volatility that actually gets realized. The market overpays for protection and lottery tickets, so the expected move it prices in is routinely wider than what actually happens. That gap is a durable, well-documented edge — and you can capture it without ever selling a naked option.
The proof is in the delta. A 16-delta Put is priced as if it has roughly a 16% chance of finishing in the money — yet historically these strikes finish in the money closer to 5% of the time. A 30-delta Put priced at ~30% odds tends to finish in the money nearer 11%. The market consistently overprices the tails, and that gap is the seller's edge.
This is why the high-probability playbook is built on defined-risk debit structures — the Debit Condor, the debit Butterfly, and directional Bull Call / Bear Put Debit Spreads. Each finances a cheaper long option with a nearer strike you sell against it, so you pay a small net debit for a wide win zone the overstated expected move rarely escapes. You are not betting on direction and you carry no open-ended risk — your max loss is the debit, known before you click, and the same overpricing that tempts option sellers is working quietly in your favor.
Delta Lies, Sigma Doesn’t — Placing Strikes
Delta is the most common way traders pick strikes — and it is fine as a shorthand. But delta drifts: it changes with every tick of price and every shift in volatility, so a "20-delta" strike this morning is a different animal by lunch. To place strikes with real consistency, anchor them to standard deviations (sigma) off the expected move instead.
Expected Move — the market’s own forecast
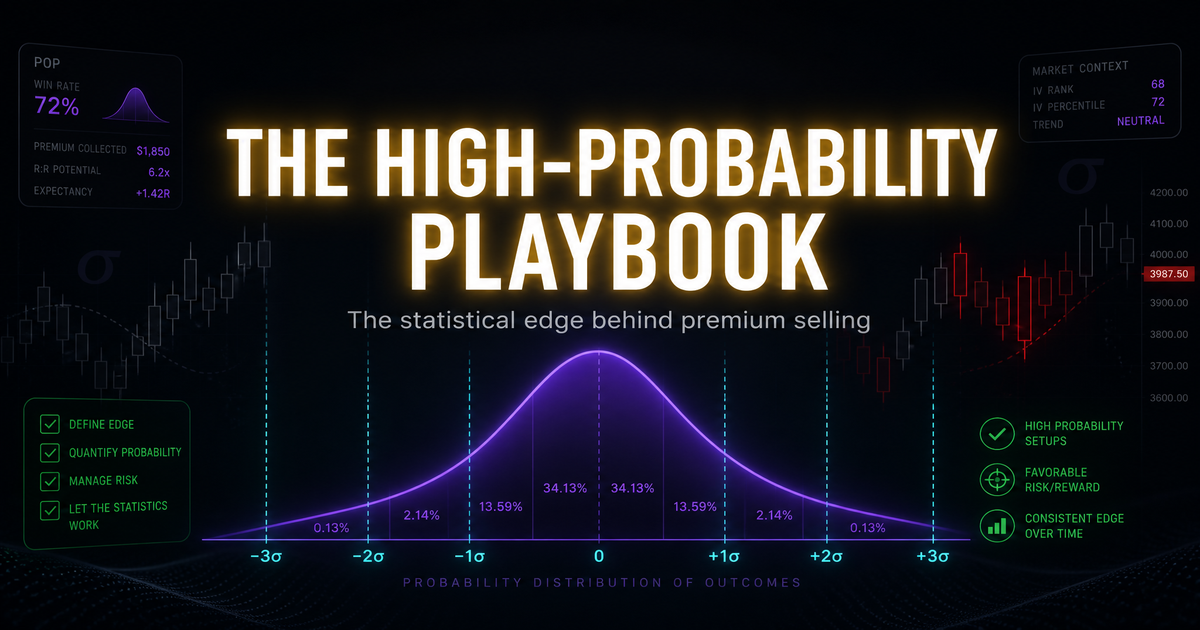
Expected Move ≈ Spot × (VIX ÷ √252) × √days. A fast field shortcut: roughly 85% of the at-the-money straddle price for that expiration. This is one standard deviation — the ±1σ band that captures about 68% of outcomes.
Sigma distance of any strike
Sigma = (Strike − Spot) ÷ (Spot × IV × √(DTE ÷ 252)). This tells you how many standard deviations a strike sits from spot — a stable, apples-to-apples measure that does not drift the way raw delta does.
The calibration that works
About 1.0–1.5σ for 0DTE debit spreads, and about 0.7–1.0σ for 7-day Debit Condors. Wider sigma = higher win rate for a slightly larger debit; tighter sigma = a cheaper debit but a smaller win zone. 1σ ≈ 68% inside.
SPXXL does this sigma math for you. The expected-move rails on the Close Zone™ and Weekly Close Zone™ are the ±1σ and ±2σ bands drawn straight from at-the-money implied volatility — so your inner win-zone strikes and outer protective wings line up with real probability, not a gut feel.
The Proven Structures
Once you know why the edge exists and where to place strikes, you pick the structure that fits the session. Every one below is defined-risk and built to capture the Volatility Risk Premium — for a small, known debit:
Buy an outer Put and an outer Call as your wings; sell a nearer Put and a nearer Call to define the win zone. You pay a small net debit and keep the maximum payoff when SPX finishes between your two inner strikes. Max loss is the debit — fixed the moment you enter. The premier neutral, range-bound structure.
Buy an option and sell a further one in the same direction to cut the cost: a Bull Call Debit Spread when you lean up, a Bear Put Debit Spread when you lean down. Reward-to-risk of roughly 1.5:1 to 3:1, with max loss capped at the debit. The workhorse for Trend and Expansion Days.
Buy one nearer and one farther strike around a sold body at your expected pin. Costs very little and pays a large multiple if SPX finishes near the center. The smartest same-day neutral structure — tiny defined cost, outsized payoff near the pin.
Selling Strangles, Cash-Secured Puts, or 0DTE Iron Condors harvests the same overpricing — but with undefined or asymmetric risk (a 0DTE Iron Condor often risks about $9 to make $1). The debit structures above capture the identical edge while capping your loss at what you paid. That is the whole point of this playbook.
Notice what these structures share: every one caps its maximum loss at the debit you pay. That single trait inverts the ugly math of premium selling — instead of winning small and risking a rare catastrophic loss, you risk a small, known amount for a wider, higher-probability payoff. Same VRP edge, defined downside.
The Management Rules That Lift Win Rate
Here is the part most traders skip — and it is where the majority of the edge actually lives. Entering a good trade is maybe half the battle. Managing it mechanically is what turns a 65% win rate into an 80%+ one.
Close the position once it has gained about half of its maximum value. Taking the winner early on a Debit Condor lifts realized win rates from roughly 65% at entry to about 80–86%. You free up capital, sidestep late-session gamma, and redeploy — win rate and Sharpe both improve.
Whether the trade is a winner or not, be out by 21 days to expiration. Research shows portfolio volatility is lowest and gamma risk is manageable when you refuse to hold a defined-risk debit position into the final three weeks. About 45 DTE is the researched ‘sweet spot’ to open a multi-day Debit Condor.
Your max loss is already capped at the debit, so the exit is about preserving capital, not survival: if the trade sheds roughly half the debit and the session thesis has broken, close it and redeploy. One clean exit beats hoping a broken setup comes back.
Notice the pattern: none of these require you to predict anything. They are rules, not opinions. The trader who follows all three mediocre-looking rules will almost always beat the "smarter" trader who negotiates with every position.
The 0DTE Filters
Zero-days-to-expiration trading is the highest-gamma, highest-stress corner of the playbook. The edge is still real, but it only survives if you filter hard for the right conditions. Monte Carlo studies of 0DTE trading point to three filters that matter most:
High-volatility days are where 0DTE traders blow up. Filtering them out cut the probability of a greater-than-20% drawdown from roughly 45% down to about 11.8% in simulation. When VIX is elevated, the honest edge is to stand aside.
The opening auction is the most chaotic, least predictable stretch of the session. Waiting about two hours lets the initial balance form and the day’s character reveal itself before you commit premium.
0DTE positions resolve fully by the close, so a bad day is a fully realized day. Capping risk near 1–2% of the account per day keeps any single session from doing lasting damage.
This is exactly what SPXXL's pre-market session classification is for. When the engine flags an Expansion Day or elevated-VIX regime, that is your signal to size down or skip the 0DTE debit trade entirely — the filter is doing its job before the bell.
Position Sizing — Kelly, Fractional
A real edge can still be ruined by betting too big. Position sizing is what converts a positive-expectancy system into a survivable one. The reference framework is the Kelly Criterion:
f* = (p×b − q) ÷ b
where p is your win probability, q is the loss probability (1 − p), and b is your payoff ratio (reward ÷ risk). The output f* is the fraction of capital the math says to risk.
Negative Kelly = no trade
If the formula returns a negative number, you have no edge on that trade — the correct size is zero. Do not ‘size down and hope’ a losing bet into a winner.
Use fractional Kelly (¼–½)
Full Kelly is far too volatile for real accounts and assumes your win-rate estimate is perfect (it never is). Trading a quarter to a half of Kelly keeps growth healthy while slashing the odds of a deep drawdown.
Cap absolute risk at 2–5%
Even defined-risk positions correlate in a crash — ‘uncorrelated’ trades all lose together on the worst day. An absolute cap of 2–5% of the portfolio on any position (and in aggregate) is the backstop Kelly alone will not give you.
The Honest Caveat — You Lose Small, Often
This playbook works. It does not print money risk-free, and any source that tells you otherwise is selling something. You deserve the honest version:
Premium sellers live with negative skew — they win often and small, then lose rarely but catastrophically, so a single 4σ day can erase months of profit. Debit structures deliberately invert that: your loss is capped at the debit you paid, so you trade the seller's rare catastrophe for a steady, defined cost of doing business. You will still lose small and often — that is the price of admission — but no single day can take the account.
And the tails are fatter than the textbook says. Real markets deliver 3σ and 4σ moves far more often than a normal distribution predicts. For a premium seller that is an existential threat; for a defined-risk debit trader it is merely another day the debit is lost — painful, survivable, and already priced into your sizing.
So here is the truthful bottom line: nothing in trading is "guaranteed." What is proven is the statistical edge of the Volatility Risk Premium — and that edge only shows up in your account when you refuse to overpay for your debit, take profits mechanically, and size so that no single lost debit ever matters. Do that with discipline and the math works for you instead of against you.
The High-Probability Playbook Checklist
This is the part to keep open while you trade. Run every candidate trade through these four gates in order. If any gate fails, the trade does not happen. No exceptions, no negotiating.
PRE-TRADE
Is there an edge here at all?
- Implied volatility is elevated vs. realized — the Volatility Risk Premium is present (the expected move is overstated, so your debit buys a wider win zone).
- Session classification is neutral or favorable — not an Expansion Day or a VIX > 25–30 regime.
- Kelly check: p×b − q is positive. If Kelly is negative, the trade size is zero. Walk away.
ENTRY
Are the strikes and structure right?
- Inner (sold) strikes anchored by sigma: ~1.0–1.5σ for 0DTE debit spreads, ~0.7–1.0σ for multi-day Debit Condors.
- Structure fits the session: Debit Condor or debit Butterfly when neutral; Bull Call / Bear Put Debit Spread when directional. Never a naked short or a credit Iron Condor.
- Multi-day trades opened near the 30–45 DTE sweet spot; 0DTE entered ~2 hours after the open, not at the bell.
- Both protective outer wings in place, so max loss is capped at the debit before the order is sent.
MANAGEMENT
Rules, not opinions.
- Take profit at ~50% of the max value of the position — this alone lifts realized win rate from ~65% to ~80–86%.
- Exit by 21 DTE regardless of P/L — never hold a debit position into the final three weeks of gamma.
- Cut the loser near 50% of the debit once the session thesis breaks — redeploy, no negotiating.
RISK
Survive the fat tail.
- Sized at fractional Kelly (¼–½), never full Kelly.
- Absolute risk on the position capped at 2–5% of the portfolio — and in aggregate across correlated debit trades.
- 0DTE daily risk kept near 1–2% of the account.
- Accepted the trade-off: every loss is capped at the debit you paid, so the rules above are about not overpaying for that debit and never letting one broken setup tempt you into oversizing the next.
Bookmark this section. The traders who win with defined-risk debit structures are not the ones with the best market view — they are the ones who run the same checklist every single day and never let a "good feeling" override a failed gate.
Put the Edge to Work on a Live Session
5 live sessions of full Elite access. Pre-market session classification, expected-move rails for sigma-anchored strikes, the Close Zone™, and the risk signals that tell you when to size down — the whole playbook, running live.
5 live sessions of full Elite access · No cost